The delivery of the first Tejas Mk1A fighter could be the moment Hindustan Aeronautics wins back investor trust, says global brokerage Jefferies. It has retained its ‘Buy’ rating on the stock with a price target of Rs 6,800, implying about 43% upside from the previous close of Rs 4,739.
In a note dated September 30, Jefferies said the Mk1A, which makes up 43% of HAL’s order book, is the key trigger for a re-rating. The stock has de-rated because of delays on the aircraft since 2024, which have raised concerns about the company’s ability to execute.
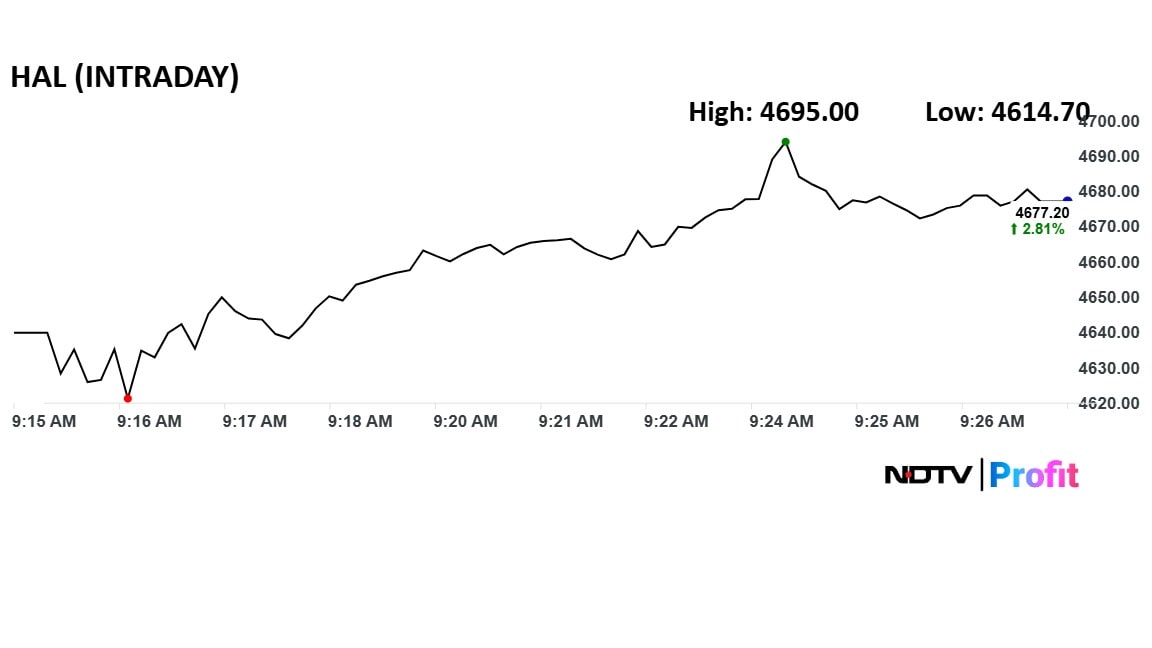
HAL share price rallied over 3% on Wednesday morning after Jefferies gave a 43% to the stock
Photo Credit: NDTV Profit
CMD confident on 10 jets this year
The note draws on interviews given by HAL CMD Ravi Kota on September 18, after the company completed delivery of the Tejas Mk1 trainer aircraft contract. Kota said he was confident of delivering Mk1A aircraft this year.
According to Jefferies, 24 airframes are ready, with a GE engine fitted and the aircraft tested. HAL has received 10 engines from GE, and 90-95% of radar and missile integration and certification is complete. The CMD’s 10-aircraft target compares with Jefferies’ own assumption of five deliveries.
Jefferies said the Indian Air Force accepting even one aircraft would be a key upside driver. In its words, that would “give confidence on the company’s abilities.”
Order book gives visibility
HAL’s order book stands at Rs 2.55 trillion, or 7.7 times FY26 revenue, with a further Rs 1.8 trillion pipeline that includes the Su-30 MKI upgrade, light utility helicopters and ALH helicopters for the Navy and Army. Jefferies expects revenue to grow at a 15% CAGR over FY26-30, with EBITDA growing at 17%. Its EBITDA margin estimate rises from 29.6% to 32.7% over the period.
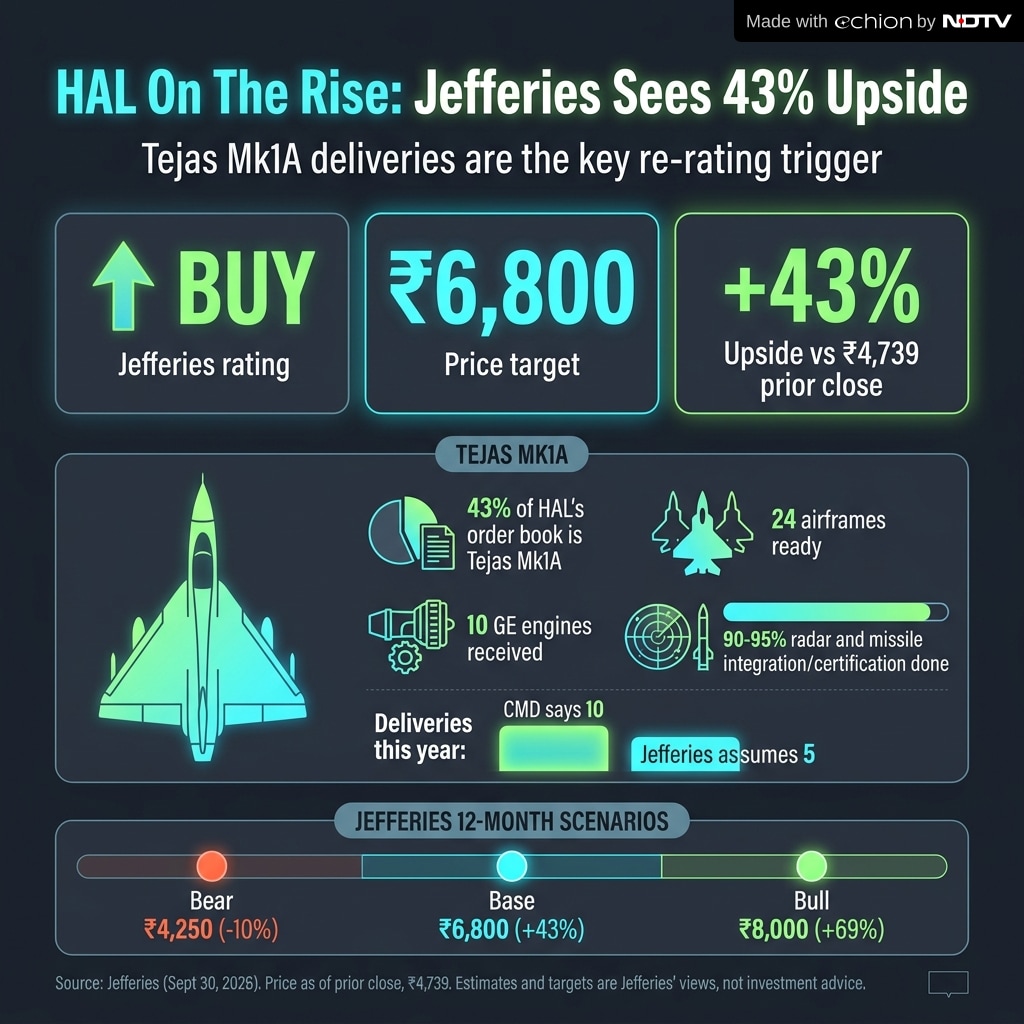
HAL target price set at Rs 6,800 by Jefferies. Here’s why
Photo Credit: NDTV Profit
HAL Valuation
The target values HAL at 35 times September 2028 earnings. Jefferies said this is 33% below the stock’s peak multiple and a 13% discount to its target multiple for Bharat Electronics. It also pointed to ROE above 22% and a debt-free balance sheet.
HAL: Bull, base and bear cases
Jefferies’ bull case is Rs 8,000 (69% upside), driven by faster defence approvals and a stronger ‘Make in India’ push. Its bear case is Rs 4,250 (a 10% fall), if defence ordering slows or margins come under pressure from higher indigenous content. That gives an upside-to-downside ratio of 6.67:1.
Jefferies flagged manufacturing execution delays and a reduced focus on defence indigenisation as the key downside risks. HAL’s 52-week range is Rs 3,479.20 to Rs 5,149.90.
ALSO READ: HAL Eases Its Engine Bottleneck Finally. Next Trigger? The GE414 Contract
